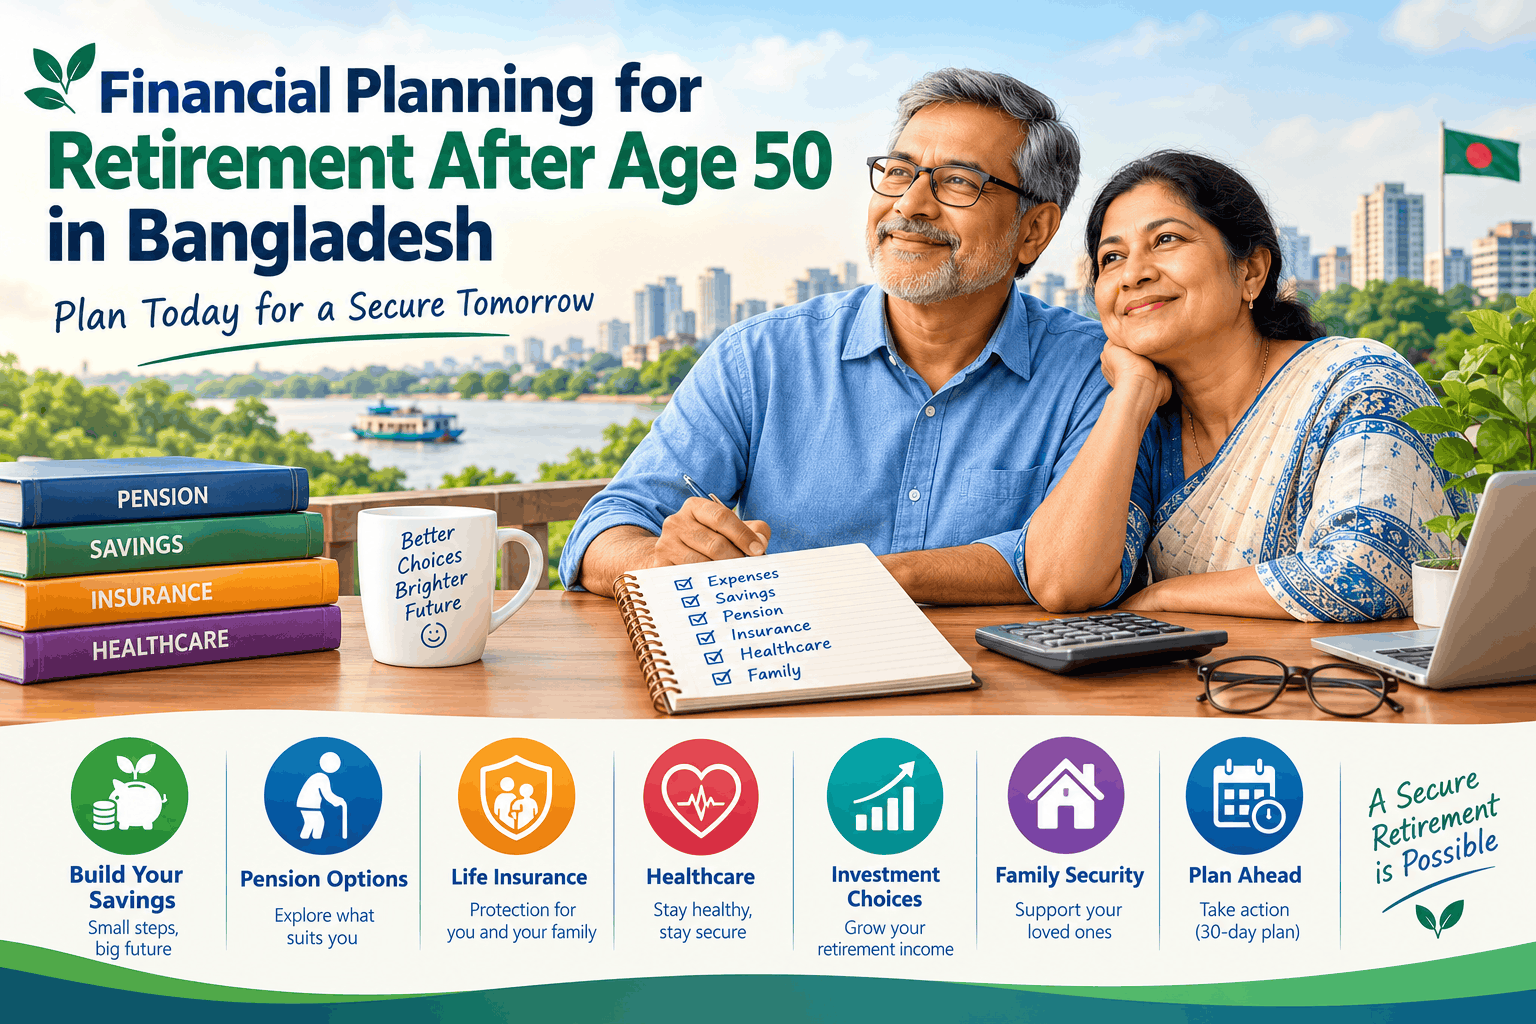
Financial Planning for Retirement After Age 50 in Bangladesh
At 52 or 55, retirement may feel much closer than it once did. You may still be paying household expenses, supporting your spouse, helping your children or managing a small business. At the same time, you may be wondering how you will maintain your lifestyle when your regular income decreases.
The good news is that financial planning for retirement after age 50 in Bangladesh can still make a meaningful difference. You may have fewer years to prepare than someone in their thirties, but you can still organize your savings, estimate future expenses, explore pension options and make better decisions about your money.
The most practical approach is to start with your current financial position. Calculate how much you need each month, identify the income you can reasonably expect after retirement, protect your emergency savings and choose financial products according to your needs.
You do not necessarily need a large amount of money to begin planning. You need a clear understanding of your finances and a realistic plan that you can maintain.
🔷 Is It Too Late to Start Retirement Planning After 50?
No. Starting retirement planning after age 50 is not too late, although your available time and financial choices may be more limited than they would have been earlier.
Your first priority should be to understand the gap between your expected retirement expenses and your available income. Once you know that gap, you can decide whether to increase your savings, reduce certain expenses, continue working longer if practical or explore suitable pension and financial products.
For example, someone aged 55 may have different options from someone aged 62. The first person may have several years to build savings before leaving full-time employment. The second may need to focus more immediately on accessible savings, regular income and healthcare expenses.
Your retirement plan should reflect your circumstances rather than an ideal savings target that may not be realistic for your household.
🔷 Step 1: Calculate Your Retirement Expenses
Before deciding how much to save, estimate how much money you will need each month after retirement.
Start with your current household expenses. Then identify which expenses may decrease, remain similar or increase when you stop working.
Identify your essential monthly expenses
Consider the following categories:
🔸 Food and household supplies: Groceries, cooking essentials and everyday necessities.
🔸Housing and utilities: Rent or home maintenance, electricity, gas, water, internet and mobile bills.
🔸Healthcare: Medicines, doctor visits, tests and other medical expenses.
🔸Transportation: Public transport, fuel and travel to medical appointments.
🔸Family responsibilities: Support for your spouse, dependent children or other family members.
🔸Debt repayments: Any loans or outstanding financial commitments.
🔸Personal expenses: Clothing, social activities, religious occasions and other needs.
Also consider expenses that do not occur every month, such as home repairs, major medical treatment or replacing essential household equipment.
🔷 Separate needs from wants
Not every expense has the same level of importance.
Essential expenses must be covered first. Other expenses may be reduced if your retirement income is limited.
For example, you might continue paying for necessary medicines while reducing non-essential shopping or expensive leisure activities. The aim is not to eliminate every enjoyable activity. It is to understand where you have flexibility.
🔷 Prepare a monthly retirement budget
Imagine that a household currently spends ৳35,000 per month. Its expected retirement budget might look like this:
🔸Food and household supplies: ৳12,000
🔸Housing and utilities: ৳6,000
🔸Healthcare and medicines: ৳5,000
🔸Transportation: ৳2,000
🔸Family support: ৳5,000
🔸Personal and other expenses: ৳5,000
🔸Illustrative monthly total: ৳35,000.
These figures are hypothetical, not an official estimate of retirement costs in Bangladesh. Your actual budget may be higher or lower depending on where you live, whether you own your home, your health and your family responsibilities.
The important point is to calculate your own expenses instead of relying on a general retirement savings target.
🔷 Step 2: Estimate Your Retirement Income and Savings Gap
After estimating your expenses, identify the money you expect to receive after retirement.
Possible sources include:
🔸Government or employer pension benefits, where applicable.
🔸Income from a business or part-time work.
🔸Rental income from property.
🔸Interest or other payments from eligible savings products.
🔸Payments from a pension scheme.
🔸Personal savings that you plan to use over time.
🔸Benefits from an insurance policy, if its verified terms provide for them.
Do not count income simply because you hope it will become available. Use documented pension entitlements, realistic business estimates and the actual terms of your financial products.
🔷 Calculate your monthly income gap
Use this simple formula:
Monthly retirement income gap = Estimated monthly expenses − Expected monthly income
Suppose your household expects to spend ৳35,000 each month after retirement.
You expect to receive ৳20,000 per month from documented pension benefits and other reasonably reliable income sources.
Your estimated monthly gap would be:
৳35,000 − ৳20,000 = ৳15,000 per month.
This means you need a plan to cover the remaining ৳15,000. Depending on your circumstances, that may involve savings withdrawals, additional income, a suitable pension arrangement or a combination of options.
🔷 Estimate a savings target
If you want to understand the size of the gap over time, you can multiply it by the number of months you want to plan for.
For example, a ৳15,000 monthly gap over five years would equal:
৳15,000 × 12 × 5 = ৳9,00,000.
This is a simple illustration of five years of expenses at an unchanged monthly gap. It is not a complete retirement capital calculation. It does not account for inflation, investment returns, taxes, emergencies or changes in income and expenses.
For a longer retirement, you may need to plan for a much longer period. Avoid assuming that a fixed savings amount will cover every future expense.
🔷 Consider inflation before setting your target
Today's money may not buy the same amount of goods and services in the future.
For example, if your current monthly expenses are ৳35,000, those same expenses could cost more several years from now. The future amount will depend on actual price changes, which cannot be predicted precisely.
When preparing your plan, review it regularly and update your expected expenses rather than assuming your current budget will remain unchanged.
🔷 Step 3: Choose Suitable Retirement Savings and Income Options
There is no single retirement savings plan that is best for everyone in Bangladesh. Your age, income, existing savings, access to funds and need for regular payments all matter.
🔷 Government or employer pension benefits
If you are eligible for a government or employer pension, obtain the relevant documents and confirm your expected entitlement.
Check when payments begin, how much you are entitled to receive, whether benefits depend on your service record and what provisions apply to your spouse or dependants.
Do not assume that every private-sector employee or self-employed person has a formal pension.
If you have no employer pension, you can still build a retirement plan using personal savings and other suitable financial arrangements.
The Universal Pension Scheme in Bangladesh
Bangladesh's Universal Pension Scheme is an option worth investigating if you are approaching retirement or do not have a traditional employer pension.
The scheme includes four categories:
🔸 Pragati: For employees and employers in private-sector institutions.
🔸Surokkha: For self-employed people and workers in informal occupations.
🔸Samata: For eligible low-income participants under the scheme's conditions.
🔸Probash: For eligible Bangladeshi expatriates.
According to the official scheme information, people aged 18–50 can generally participate, while people over 50 may participate under special consideration by making contributions continuously for 10 years. The conditions and payment arrangements should be confirmed directly with the National Pension Authority before registering.
If you are already in your fifties or sixties, pay particular attention to the contribution period, the age at which payments become available, your required monthly contribution and the rules governing access to funds.
Visit the official Universal Pension Scheme website to review the current scheme information and eligibility requirements.
Do not commit to a contribution until you understand how it fits your household budget and what the current rules mean for your retirement timeline.
🔷 Bank savings accounts and fixed deposits
Bank savings accounts and fixed deposits may be useful for people who want to keep money in familiar financial products.
A savings account can provide convenient access to money, while a fixed deposit generally keeps funds committed for an agreed period under specified terms.
Before choosing a deposit, check:
🔸The current interest or profit rate.
🔸The deposit term and maturity date.
🔸Early withdrawal conditions and penalties.
🔸Applicable taxes and charges.
🔸How interest or profit is paid.
The institution's financial position and relevant protections.
Rates and conditions can change. Do not assume that an advertised rate will remain available indefinitely.
Also remember that interest income may not keep pace with rising living costs. Consider how inflation could affect the purchasing power of your savings.
🔷 Government savings certificates and other savings instruments
Eligible government savings instruments may be relevant to your retirement plan, depending on the product's current rules.
Check the eligibility requirements, purchase limits, maturity conditions, payment arrangements, applicable tax treatment and current rates before investing.
Some products are designed for specific categories of savers. For example, an instrument intended for eligible pensioners may not be available to everyone over age 50.
Confirm eligibility through official government sources rather than relying on an informal recommendation.
🔷 Personal savings and an emergency fund
Personal savings can help you cover expenses without depending entirely on a pension or investment income.
If possible, keep money for unexpected costs separate from money intended for long-term retirement needs.
Your emergency reserve may help with an urgent medical bill, a necessary home repair or a temporary interruption in income.
The appropriate amount depends on your household's essential expenses, existing insurance and other available resources. A person with unstable income may need a different reserve from someone with reliable pension payments.
Avoid committing every available taka to a product that makes early access difficult.
🔷 Step 4: Evaluate Life Insurance for Retirement Planning
Life insurance may form part of a retirement plan, but it is important to understand what a policy actually does.
Some policies are primarily intended to provide financial protection if the insured person dies. Other policies may include savings, maturity or scheduled-payment features, depending on their terms.
These purposes are not interchangeable.
🔷 Understand protection versus savings
A protection-focused policy may help provide financial support to eligible beneficiaries if the insured person dies while the policy is in force and the claim meets the policy conditions.
A savings-oriented or endowment policy may provide a payment at maturity if the contract specifies one and the applicable conditions are satisfied.
A pension-oriented insurance product may have a different payment structure again.
Before purchasing any policy, determine which purpose it serves and whether it addresses a genuine need in your retirement plan.
🔷 Questions to ask before buying a policy after age 50
Ask the insurer or authorized adviser to explain:
🔸 Is my current age eligible for this particular policy?
What premium must I pay, and for how long?
🔸What benefits are contractually specified?
🔸What happens if I stop paying premiums?
🔸When can I receive any maturity or scheduled payment?
🔸What exclusions, waiting periods or other limitations apply?
🔸What happens if I die during the policy term?
🔸Are any bonuses or projected benefits conditional rather than guaranteed?
🔸What happens if I surrender the policy early?
How would the policy fit alongside my emergency savings and other retirement income?
Request the relevant policy illustration and written terms. Do not rely solely on verbal statements about future returns or benefits.
🔷 Exploring options from National Life Insurance PLC
National Life Insurance PLC provides information about its insurance services and customer-care channels through its official website. Its published company materials also list insurance products with pension-related names.
However, a product's appearance in company materials does not establish that it is currently available to every applicant or suitable for someone over 50.
If you are considering an insurance product for retirement planning, visit National Life Insurance PLC and ask an authorized adviser about currently available options, age eligibility, premium requirements, policy duration, benefits and exclusions.
Compare the written terms with your budget and other financial options before making a decision.
An insurance policy should complement your retirement plan where appropriate, not replace emergency savings or be treated as an automatic guarantee of retirement income.
🔷 Step 5: Prepare for Healthcare Costs and Inflation
Healthcare is an important part of retirement planning because medical expenses can be difficult to predict.
Your budget should account for routine check-ups, prescribed medicines, tests, transport to healthcare facilities and the possibility of larger unexpected expenses.
🔷 Create a separate healthcare reserve
If your income allows, set aside money for medical expenses in a separate, accessible account or reserve.
Review the amount periodically based on your actual medical spending and available financial support.
If you already have health insurance, check what it covers, which exclusions apply, whether particular treatments have limits and how claims work.
Do not assume that every medical expense will be reimbursed.
🔷 Protect the purchasing power of your savings
Inflation can gradually reduce what your savings can buy.
For example, someone who plans retirement around a fixed monthly amount may find that the budget becomes insufficient as food, utilities, transport and medical expenses rise.
To reduce this risk:
🔸 Review your budget at least annually.
🔸 Avoid depending entirely on a single source of income.
🔸 Compare current deposit rates with changing living costs.
🔸 Keep suitable funds available for emergencies.
🔸 Reassess your savings and income plan when circumstances change.
No savings or investment option eliminates every financial risk. The goal is to understand the trade-offs and build a plan that remains practical as your needs evolve.
🔷 Step 6: Protect Your Spouse and Dependants
Retirement planning is not only about your own expenses. It should also consider the people who depend on you financially.
If you are married, discuss your expected retirement income, household expenses, debts and financial priorities with your spouse.
Make sure both of you understand where important financial documents are kept and how to access relevant accounts and policy information.
Review the following:
🔸 Outstanding loans and financial obligations.
🔸 Beneficiary and nominee details where applicable.
🔸 Existing life insurance and its actual benefits.
🔸 Pension or survivor-benefit eligibility.
🔸 Ownership and documentation of important assets.
🔸 Financial arrangements for dependants.
If your children are financially independent, you may be able to reduce some family-support expenses over time. If you support a dependent family member, include that responsibility in your retirement budget.
Do not assume that a life insurance policy automatically pays every beneficiary under every circumstance. The applicable policy wording and claim requirements determine the benefits.
🔷 Your 30-Day Retirement Planning Action Plan
You do not have to complete every financial decision immediately. Use the next 30 days to understand your situation and establish a practical starting point.
🔷 Week 1: Understand your current finances
🔸 Write down your monthly household expenses.
🔸 List your income sources and existing savings.
🔸 Record your outstanding debts.
🔸 Gather pension statements, bank records and insurance documents.
🔸 Identify any missing financial information.
🔷 Week 2: Estimate your retirement needs
🔸 Calculate your essential monthly expenses.
🔸 Estimate your expected income after retirement.
🔸 Work out your monthly income gap.
🔸 Include healthcare and emergency expenses.
🔸 Consider how future price increases could affect your budget.
🔷 Week 3: Review your options
Check any pension benefits you may already qualify for.
🔸 Review the official Universal Pension Scheme rules if relevant.
🔸 Compare accessible savings with longer-term financial products.
🔸 Ask insurers for written policy terms and eligibility details.
🔸 Avoid committing money before understanding withdrawal restrictions and charges.
🔷 Week 4: Put your plan into action
🔸 Decide on a realistic savings amount.
🔸 Separate emergency funds from longer-term savings where possible.
🔸Set up a sustainable savings routine.
🔸 Discuss important financial decisions with your spouse or family.
🔸 Choose a date to review your plan again.
Your first plan does not have to be perfect. It needs to be clear enough to help you make better decisions and flexible enough to change when your circumstances change.
🔷 Frequently Asked Questions
1. Is 50 too old to start retirement planning in Bangladesh?
No. Starting at 50 or later can still help you organize your savings, estimate future expenses, review pension eligibility and prepare for healthcare costs. Your available time and financial options will depend on your age, income, existing savings and retirement goals.
2. How much money do I need for retirement in Bangladesh?
There is no universal retirement savings amount that suits every household. Calculate your expected monthly expenses, subtract your reliable retirement income and estimate how long you may need to cover the remaining gap. Include healthcare, emergencies and possible increases in living costs.
3. Can I join the Universal Pension Scheme after age 50?
The official Universal Pension Scheme information states that people over 50 may participate under special consideration, subject to continuous contributions for 10 years. Confirm the current eligibility requirements, contribution rules and payment timing directly with the National Pension Authority.
4. How can I prepare for retirement with a low income?
Start by recording essential expenses, reviewing debts and identifying an affordable amount to save regularly. Check whether you qualify for relevant pension arrangements and avoid committing money you may need for essential living costs. Small, sustainable steps can help you understand and improve your financial position over time.
5. Should I choose a bank fixed deposit or life insurance for retirement?
These products serve different purposes. A fixed deposit has specific deposit, interest and withdrawal terms, while life insurance may provide protection or contractual savings-related benefits depending on the policy. Compare their terms, liquidity, costs, risks and suitability before deciding.
6. How should I prepare for medical expenses after retirement?
Estimate routine healthcare costs, review any existing health insurance and set aside accessible funds for unexpected expenses where possible. Check policy limits and exclusions carefully, and update your budget as your medical needs change.
7. What should I check before buying retirement-related life insurance?
Confirm your age eligibility, premium amount, payment period, policy duration, written benefits, exclusions, surrender conditions and claim requirements. Ask whether any projected bonus or return is guaranteed under the contract. Compare the policy with your other savings and retirement-income options before purchasing.
8. Does life insurance guarantee a financially secure retirement?
No. Life insurance can provide specified protection or other benefits under a policy's terms, but it does not automatically cover all retirement expenses or guarantee financial independence. A retirement plan should consider income, savings, healthcare, debt, inflation and family responsibilities.
🔷 Final Thoughts
Financial planning for retirement after age 50 in Bangladesh begins with understanding your actual financial position.
Estimate your expenses, identify your likely retirement income, calculate any shortfall and review the financial options available to you. Give particular attention to healthcare costs, inflation, emergency savings and the needs of your spouse or dependants.
If you are considering a pension scheme or retirement-related insurance product, verify the current eligibility requirements and read the relevant terms before making a commitment.
National Life Insurance PLC can be a starting point for learning about its currently available insurance options. Visit its official website or contact an authorized adviser to ask about eligibility, premiums, policy benefits and applicable conditions.
The most useful retirement plan is one that reflects your circumstances, protects your essential needs and gives you a realistic way to prepare for the years ahead.
Disclaimer: This article provides general financial education, not individualized financial, investment, tax or insurance advice. Pension rules, product availability, rates and policy terms can change. Verify current information with the relevant official authority or financial institution before making a decision.
← Back to Insights
NLI Archive / 2026
Trending Analysis
Retirement Planning After 50 in Bangladesh: A Practical Guide
N
NLI Editorial
© National Life Insurance Co. Ltd.
Share:
FB
LN