Survival Benefit vs DPS: Which Is Better for Your Savings and Financial Goals?
Imagine you are a salaried professional in Bangladesh. Every month, after paying rent, groceries, bills, family expenses, and other costs, you try to keep aside ৳5,000 for the future.
But then comes the difficult question: Where should that money go?
You could put it into a DPS and build disciplined savings over time. Or, you might consider a life insurance savings plan with Survival Benefit features, where long-term savings can be combined with financial protection.
At first glance, both options may look similar because both can involve regular payments and future financial benefits. But they are designed for different purposes.
সহজভাবে বললে, শুধু ভবিষ্যতের জন্য টাকা জমাতে চান, নাকি টাকা জমানোর পাশাপাশি পরিবারের আর্থিক সুরক্ষাও চান—এই প্রশ্নের উত্তরই আপনার decision-making-এর বড় অংশ।
So, when comparing Survival Benefit vs DPS in Bangladesh, which option is better? The honest answer is: neither is automatically better for everyone. The right choice depends on your savings goal, time horizon, financial responsibilities, need for protection, and the specific terms of the product you choose.
This guide explains the differences in simple language so you can make a more informed decision.
🔷 Survival Benefit vs DPS: Which Is Better?
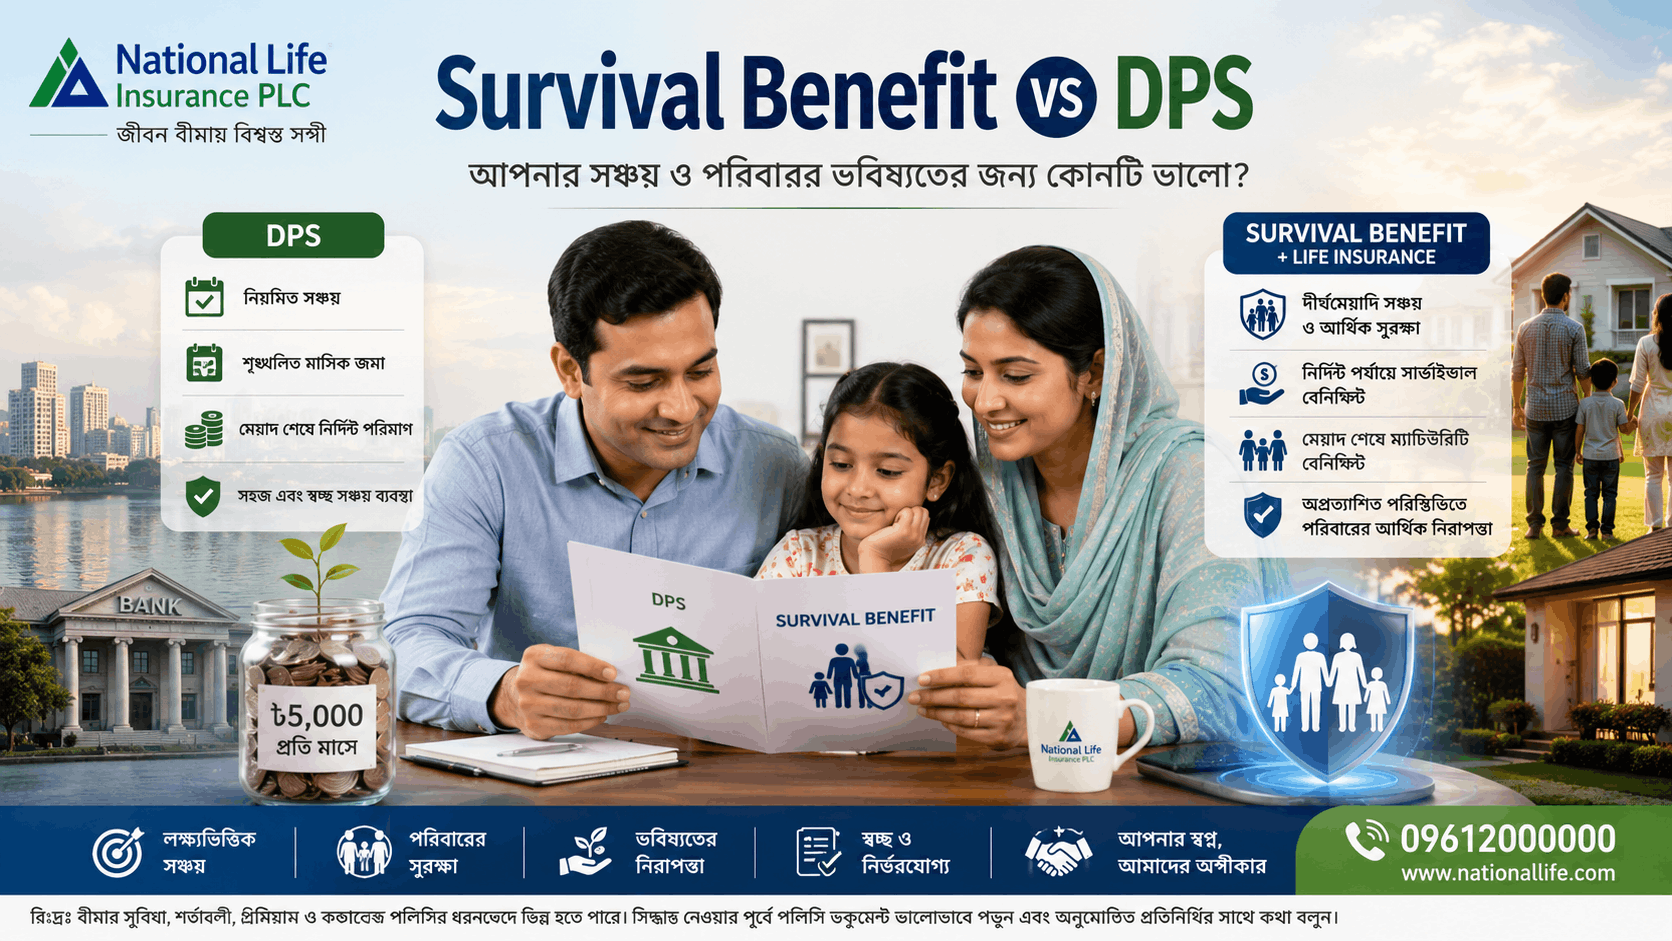
Survival Benefit and DPS can both support disciplined saving, but they have different core purposes. A DPS is primarily an installment-based savings scheme, while a Survival Benefit life insurance plan can combine long-term savings with insurance protection and benefits according to its policy terms. Your best choice depends on whether your priority is mainly accumulating savings or building savings together with family financial protection.
🔷 Survival Benefit vs DPS: Quick Comparison
🔸 Primary Purpose:
A Survival Benefit plan combines long-term savings with insurance-related protection, while a DPS is mainly designed for regular and disciplined savings.
🔸 Long-Term Savings:
Both options can help you build savings over time. However, the savings structure and benefits depend on the specific insurance policy or DPS scheme.
🔸 Maturity Benefit:
A Survival Benefit policy may provide maturity benefits according to its policy terms and applicable benefits. A DPS provides the amount determined by the financial institution’s scheme terms.
🔸 Family Protection:
Survival Benefit plans can include life insurance protection, helping provide financial support to your family. A DPS is primarily a savings arrangement and does not generally focus on life insurance protection.
🔸 Life Insurance Coverage:
Insurance coverage may be included in a Survival Benefit policy, depending on the selected plan. DPS is not primarily designed to provide life insurance coverage.
🔸 Regular Payments:
Survival Benefit policies may require regular premium payments, depending on the plan. DPS generally requires regular installments according to the selected scheme.
🔸 Financial Planning:
A Survival Benefit plan can support both long-term savings and family protection goals. A DPS can be useful when your main objective is to develop a regular savings habit.
🔸 Suitable For:
A Survival Benefit plan may be suitable for people who want long-term savings plus financial protection, while a DPS may be more suitable for those primarily focused on systematic savings.
Important: The exact benefits, returns, premiums, maturity values, and insurance coverage can vary by provider and product. Always review the official policy or scheme terms before making a financial commitment.
🔷 What Is Survival Benefit?
Survival Benefit is an insurance-related benefit paid to a policyholder when the insured person survives specified stages or the relevant policy period, depending on the plan. It is commonly associated with insurance products designed to provide financial benefits during or at the end of a policy term.
This is important because life insurance is not always simply about receiving money at the very end of a policy. Some insurance products are structured around anticipated or survival benefits, while others focus mainly on maturity or protection.
National Life Insurance PLC's 2024 Annual Report lists several insurance products, including Three Payments Anticipated Endowment Insurance, Five Payments Anticipated Endowment Insurance, Monthly Savings Insurance, Family Savings & Income Insurance Plan, Pension Insurance, and other savings-oriented insurance products. The report also separately records claims under maturity and Survival Benefit categories.
🔷 How Does Survival Benefit Generally Work?
The basic idea is straightforward.
You choose an insurance policy based on your financial objective. You pay the required premium according to the policy schedule. If the policy provides Survival Benefits, payments may become payable when the specified conditions or milestones are reached.
Depending on the policy, you may also have a maturity benefit if you survive the full policy term.
At the same time, because the arrangement is insurance-based, eligible beneficiaries may receive applicable protection benefits if the insured event occurs during the policy period, subject to the policy's terms and conditions.
That combination is what makes insurance-linked savings different from a simple savings deposit.
🔷 Why Do People Consider Survival Benefit Plans?
A person may consider this type of plan when the goal is not simply:
“I want to save money.”
Instead, the goal may be:
“I want to save for my child's education while also thinking about what would happen to my family if I were no longer earning.”
For a parent, newly married couple, business owner, or salaried professional supporting family members, that distinction can matter.
অর্থাৎ, আপনি শুধু টাকা জমাচ্ছেন না—আপনার পরিবারের future financial protection-এর কথাও বিবেচনা করছেন।
However, not every Survival Benefit policy works in exactly the same way. Benefit amounts, payment schedules, bonuses, maturity conditions, premiums, surrender provisions, and insurance coverage must be checked in the specific policy document.
🔷 What Is DPS?
DPS, or Deposit Pension Scheme, is an installment-based savings arrangement where a customer deposits a fixed or agreed amount regularly for a specified period and receives the applicable amount according to the scheme's terms.
Bangladesh Bank describes Deposit Pension Scheme as an installment-based small savings scheme in which customers deposit affordable installments for a fixed term and receive an amount upon completion of the term.
In practical terms, DPS works like a structured monthly savings habit.
Suppose you decide that saving money every month is difficult because there is always another expense. A DPS can create discipline by making regular saving part of your financial routine.
For example:
🔸You choose a monthly installment.
🔸You select the applicable tenure.
🔸You deposit according to the schedule.
🔸The financial institution calculates the maturity amount according to its applicable terms.
The exact return, maturity amount, early encashment rules, and installment requirements depend on the provider and product. Bangladesh Bank's guidance also recognizes that deposit scheme parameters such as installment amount, tenure, interest/profit rate, and premature encashment can be configured according to the financial institution's policy.
🔷 Why Is DPS Popular in Bangladesh?
For many households, the biggest challenge is not earning money—it is keeping money aside consistently.
A person may say:
“I will save whatever is left at the end of the month.”
But often, nothing is left.
DPS changes that habit by making savings a planned commitment.
A young employee may use DPS for a future wedding. A parent may save for education expenses. A business owner may build a personal reserve. Someone approaching retirement may use regular deposits as one part of a broader financial plan.
The key strength is simplicity: regular saving for a defined goal.
🔷 Survival Benefit vs DPS: What Is the Biggest Difference?
The biggest difference is purpose.
A DPS is primarily designed around systematic savings. A Survival Benefit-based insurance plan can combine savings with insurance protection, depending on the policy.
That difference becomes clearer when you look at the following factors.
1. Maturity Benefits
Both arrangements can provide a financial amount at the end of a defined period, but the way that amount is determined can be different.
With a DPS, the maturity amount is generally based on the installment amount, tenure, and applicable interest or profit structure of the scheme.
With an insurance savings plan, maturity benefits depend on the specific policy. The policy may include a sum assured, bonuses where applicable, Survival Benefits, or other benefits according to its terms.
Therefore, it is not sensible to compare only two headline maturity amounts without comparing the full product structure.
Before choosing, ask:
🔸What amount am I expected to pay?
For how long?
🔸What do I receive at maturity?
🔸Are there Survival Benefits during the term?
🔸What happens if I die during the policy?
🔸What happens if I stop paying?
🔸What are the surrender or paid-up conditions?
These questions can reveal the real difference between DPS and insurance.
2. Long-Term Savings
Both can support long-term savings, but your objective matters.
If your target is a clearly defined amount for a future expense, a DPS may be a straightforward choice.
For example, you may want to accumulate money for:
🔸A child's university education
🔸A wedding
🔸A home-related expense
🔸A future business need
🔸An emergency reserve
🔸Retirement preparation
An insurance savings plan may be more relevant when the savings target exists alongside a need for life protection.
For example, a parent may think:
“I want to build money for my child's future, but I also want a financial safety net for my family.”
That is a different financial objective from saving alone.
3. Family Protection
This is one of the most important differences in a DPS vs Life Insurance comparison.
A conventional DPS is primarily a savings product. Its main purpose is to accumulate money through regular deposits.
Life insurance, on the other hand, is designed around financial protection. Certain savings-oriented insurance policies can combine that protection with long-term savings or maturity benefits.
Consider a family where one person earns most of the household income.
If that person dies unexpectedly, the family may still have to manage:
🔸Children's education
🔸Rent or housing costs
🔸Food and daily expenses
🔸Loan obligations
🔸Parents' support
🔸Future financial goals
Savings alone may not address every risk.
Insurance is designed to address a different problem: what happens to your family's financial plan if the income provider is no longer there?
This does not mean every insurance product is automatically better. It means you should compare products based on what they are actually designed to do.
4. Financial Planning
Good financial planning usually starts with a question:
“What am I trying to protect or achieve?”
If your answer is “I want to accumulate money,” a DPS may fit that particular objective.
If your answer is “I want to accumulate money while creating financial protection for my family,” an appropriate insurance savings plan may deserve consideration.
The decision should also account for your emergency fund, existing insurance, debt, income stability, dependents, and other financial commitments.
🔷 A Bangladesh-Specific Example: DPS or Survival Benefit?
Let's consider Rafiq, a 32-year-old professional living in Bangladesh.
He can set aside ৳5,000 per month for a long-term goal.
His first option is a DPS.
He uses the monthly deposit to create a disciplined savings habit. His objective is simple: build a future fund according to the DPS's terms.
His second option is an insurance-based savings plan with Survival Benefit features.
His objective is broader. He wants to save for his child's future, but he also wants insurance protection as part of his financial plan.
The important point is that we should not assume one option will produce a better financial result without knowing the exact product terms.
The example is hypothetical and does not represent an actual National Life Insurance PLC return.
Instead, it demonstrates something more important:
Rafiq is not choosing between two identical products. He is choosing between two different approaches to financial planning.
If his priority is straightforward monthly savings, DPS may be enough for that goal.
If he wants savings plus insurance protection, an appropriate insurance plan may be worth considering.
🔷 Which Option Is Better for You?
There is no universal winner in the Survival Benefit vs DPS comparison.
Your decision should begin with your personal financial situation.
Consider DPS if:
🔸 Your main objective is disciplined monthly saving.
🔸 You have a specific short- or medium-term savings goal.
🔸 You prefer a straightforward deposit-based structure.
🔸You already have adequate life insurance protection.
🔸 You understand and accept the DPS provider's terms.
🔸Your priority is building a savings balance rather than combining savings with insurance protection.
🔷 Consider Survival Benefit if:
🔸You are planning for a longer financial horizon.
🔸You want savings and insurance protection together.
🔸You have family members who depend on your income.
🔸You are planning for children's future expenses.
🔸You want your financial plan to include protection against unexpected events.
🔸You understand the premium, policy term, benefits, exclusions, and conditions.
🔷 What If You Want Both?
You do not necessarily have to treat DPS vs Insurance as an either-or decision.
Some people may use different financial products for different purposes.
For example:
Emergency fund → DPS or liquid savings → Life insurance protection → Long-term goal planning
The right combination depends on your income, responsibilities, budget, and existing financial arrangements.
The important thing is not to buy several products simply because they sound attractive. Each product should have a clear role in your financial plan.
🔷 What Should You Check Before Choosing a Savings Plan in Bangladesh?
Before signing up for any DPS or insurance savings plan, compare the details carefully.
🔷 Check the Payment Requirement
Make sure the monthly or periodic payment is realistic for your income.
A plan that looks attractive but becomes difficult to maintain can create financial pressure.
🔷 Understand the Term
A five-year goal is different from a 15- or 20-year financial commitment.
Choose a tenure that matches your actual objective.
🔷 Compare the Maturity Benefit
Do not look only at a promotional figure.
Ask how the maturity amount is calculated and whether any component is guaranteed, projected, conditional, or bonus-based.
🔷 Understand Early Exit Rules
Life does not always follow the original plan.
You may face a job change, business problem, family emergency, or other financial pressure.
Understand the rules for premature encashment, surrender, paid-up status, or account closure before committing.
🔷 Check Insurance Protection
If you are considering life insurance, understand:
🔸 Who is covered?
🔸Who is the nominee?
🔸What event triggers a claim?
🔸What benefits are payable?
🔸What exclusions apply?
🔸What happens if premiums are missed?
Never assume that two insurance policies provide identical protection.
🔷 Read the Policy Documents
This is especially important for insurance.
Benefits depend on the specific policy terms and conditions.
If a sales representative gives you a verbal explanation, compare it with the official policy document before making a decision.
🔷 Why Consider National Life Insurance PLC for Long-Term Financial Planning?
For people considering Life Insurance Savings in Bangladesh, National Life Insurance PLC offers a broad range of insurance products designed for different financial needs.
Its 2024 Annual Report lists products including Endowment Insurance, Three Payments Anticipated Endowment Insurance, Five Payments Anticipated Endowment Insurance, Monthly Savings Insurance, Pension Insurance, Children Education Security Plan, Family Savings & Income Insurance Plan, Monthly Small Savings Insurance, and Takaful savings products, among others.
That product diversity matters because financial goals are not identical.
A young professional may think about long-term savings. A parent may focus on children's education. A family may prioritize financial protection. Someone approaching retirement may focus on pension planning.
National Life Insurance PLC states that it began operations in 1985 and has developed a diversified product portfolio and nationwide branch network. Its official company profile currently lists 705 branches.
The company's 2024 Annual Report also reports claims across categories including maturity claims and Survival Benefit claims, demonstrating that these benefits form part of its life insurance business.
For a customer, the important point is not simply the name of the company. It is whether the specific policy fits your financial objective.
If you are considering a National Life Insurance PLC policy, ask for the official policy terms and understand the premium, tenure, maturity benefits, Survival Benefits where applicable, insurance coverage, exclusions, and other conditions before purchasing.
A good financial decision is one you understand—not one you make because someone says it is “the best.”
🔷 DPS vs Life Insurance: Questions to Ask Yourself
Before choosing between a DPS and a Survival Benefit-based insurance plan, ask yourself five simple questions:
🔸What am I saving for?
🔸 How long can I keep the money committed?
🔸Does anyone depend on my income?
🔸Do I already have enough life insurance protection?
🔸Can I comfortably maintain the required payment?
These questions often make the decision much easier.
If your answer focuses mainly on accumulation, a DPS may be suitable.
If your answer includes both accumulation and family protection, an insurance savings plan may deserve closer consideration.
🔷 How Does Inflation Affect DPS and Survival Benefit Savings?
Inflation is one of the most important factors to consider when planning long-term savings because the purchasing power of money can decrease over time.
For example, suppose you save ৳10 lakh today. After 10 or 15 years, the same amount may not buy the same goods or services because prices can rise.
This means looking only at the final maturity amount may not give you the complete picture.
When comparing Survival Benefit vs DPS, consider:
🔸How long you plan to save
🔸What your future financial goal may cost
🔸Whether your contribution can remain affordable
🔸The purchasing power of the expected maturity benefit
🔸Whether your financial plan should be reviewed as your income changes
🔷 Why Does This Matter?
Imagine a parent planning for a child's university education 12 years from now.
The parent should not simply ask:
“How much money will I receive?”
A better question is:
“Will the money I receive be enough for the goal I am planning today?”
Long-term financial planning should consider both savings growth and the future cost of achieving your goal.
🔷 What Happens If You Cannot Continue Your Payments?
One of the most overlooked questions when comparing DPS vs Life Insurance is what happens when your financial situation changes.
Your income may be affected by:
🔸Job loss
🔸Business difficulties
🔸Family emergencies
🔸Unexpected expenses
🔸Career changes
🔸Changes in household responsibilities
Before choosing a financial product, understand what happens if you cannot continue making payments.
🔷 For a DPS
The financial institution's terms determine what happens after missed installments, premature closure, or early withdrawal.
🔷 For Life Insurance
The consequences can depend on the policy and may involve provisions such as:
🔸 Grace period
🔸Paid-up status
🔸Surrender value
🔸Policy loan, where applicable
🔸Reinstatement
🔸Other policy-specific conditions
Never assume that the amount you have paid is automatically the amount you can withdraw.
Always check the official terms before committing to a long-term financial product.
🔷 Survival Benefit vs DPS Based on Your Life Stage
Your financial priorities often change as you move through different stages of life.
🔷 Young Professional
Your priorities may include:
🔸Building a savings habit
🔸Creating an emergency fund
🔸Starting life insurance protection
🔸Planning future major expenses
A DPS may help with disciplined savings, while life insurance may help establish early financial protection.
🔷 Newly Married Couple
Financial priorities may expand to include:
🔸Housing
🔸Future children
🔸Family protection
🔸Long-term savings
A combination of savings and appropriate insurance protection may become more relevant.
🔷 Parent With Children
Your financial responsibilities may include:
🔸School fees
🔸University education
🔸Daily family expenses
🔸Future marriage costs
🔸Protecting the earning member's income
At this stage, family protection can become as important as savings.
🔷 Mid-Career Professional
You may be thinking about:
🔸Retirement
🔸Children's higher education
🔸Debt management
🔸Wealth accumulation
🔸Family security
A broader financial strategy may be needed instead of relying on a single savings product.
🔷 Near Retirement
Your priorities may shift toward:
🔸Retirement income
🔸Capital preservation
🔸Healthcare expenses
🔸Dependents
🔸Estate and family planning
The appropriate financial products should be evaluated based on your retirement needs and existing assets.
The best savings decision at age 25 may not be the best decision at age 45.
🔷 Common Myths About Survival Benefit and DPS
Myth 1: DPS and Life Insurance Are the Same
Fact: They may both involve regular payments, but they have different primary purposes. DPS mainly focuses on systematic savings, while life insurance is designed around financial protection and may include savings benefits depending on the policy.
Myth 2: The Highest Maturity Amount Is Always the Best Choice
Fact: Maturity value is only one part of the comparison. You should also consider protection, payment commitments, liquidity, policy conditions, and your actual financial objective.
Myth 3: Savings Alone Are Enough to Protect a Family
Fact: Savings can provide financial resources, but they are not necessarily a substitute for life insurance protection.
Myth 4: Every Survival Benefit Policy Works the Same Way
Fact: Survival Benefits, maturity benefits, premiums, policy terms, surrender provisions, and coverage can vary between products.
Myth 5: You Must Choose Either DPS or Insurance
Fact: Depending on your income and financial objectives, you may use different products for different purposes.
🔷 A Simple 60-Second Decision Test
Still confused between Survival Benefit vs DPS?
Answer these questions:
Do I mainly want to accumulate money?
→ Consider a suitable savings option such as DPS.
Do I want savings plus life insurance protection?
→ Consider a suitable insurance savings plan.
Does my family depend heavily on my income?
→ Make life insurance protection an important part of your financial planning.
Do I already have adequate life insurance?
→ A DPS may complement your existing protection by helping with a specific savings goal.
Could I need this money soon?
→ Carefully review liquidity and early-exit rules before choosing a long-term product.
Can I comfortably maintain the payment for the full term?
→ If not, reconsider the amount or product structure.
This simple test does not replace professional financial advice, but it can help you identify what matters most before comparing specific products.
🔷 The 5-Point Financial Planning Rule
Before choosing between DPS and Survival Benefit, remember these five principles:
1. Save for a Purpose
Give every long-term savings commitment a clear financial goal.
2. Protect Your Income
If others depend on your earnings, consider the financial consequences of losing that income.
3. Keep Emergency Money Separate
Do not assume every long-term savings product is suitable for emergency access.
4. Understand Before You Sign
Read the policy or scheme documents and ask questions about anything you do not understand.
5. Review Your Plan
Your income, family responsibilities, goals, and expenses can change.
A financial plan should evolve with your life.
🔷 Final Thoughts: Survival Benefit vs DPS in Bangladesh
Let's return to Rafiq.
He started with a simple question:
“Where should I put my monthly savings?”
But after understanding the difference between DPS and insurance, he realizes that the better question is:
“What job do I want my money to do?”
If the job is simply to build disciplined savings for a future goal, DPS can be a practical option.
If the job is to support long-term savings while also providing insurance protection, a suitable Survival Benefit or other savings-oriented life insurance policy may offer a broader approach—depending entirely on its terms.
That is the real lesson behind Survival Benefit vs DPS.
DPS and insurance are not necessarily direct substitutes. They can solve different financial problems.
For Bangladeshis planning for children's education, retirement, family security, or other long-term goals, the right decision starts with understanding the difference between saving money and protecting the financial plan behind that money.
If you are considering an insurance-based savings solution, explore the available options from National Life Insurance PLC, review the official policy documents carefully, and speak with an authorized representative about which plan matches your financial goals and ability to pay.
Your future deserves more than a quick comparison of returns. It deserves a financial plan built around your goals, your family, and your long-term security.
← Back to Insights
NLI Archive / 2026
Trending Analysis
Survival Benefit vs DPS: Which Is Better for Your Savings and Financial Goals?
N
NLI Editorial
© National Life Insurance Co. Ltd.
Share:
FB
LN