Best Age to Buy Life Insurance in Bangladesh: When Should You Start?
Imagine a young professional in Bangladesh named Rahim. He is 27, earns a regular salary, and currently has only a few major responsibilities. One day, a friend asks him, “তুমি life insurance করেছ?”
Rahim laughs.
“আমি তো এখনো young. এখনই insurance কেন?”
It is a very common thought.
But a few years later, Rahim may get married. Then there may be children, parents depending on his income, education costs, a home loan, business plans, or other family responsibilities. Suddenly, the question is no longer “Do I need life insurance?” It becomes “Did I start planning early enough?”
🔷 What Is the Best Age to Buy Life Insurance?
There is no single perfect age to buy life insurance. The best time is generally when you have people who depend on your income, financial responsibilities, or long-term goals that you want to protect. Starting earlier may also have advantages because age can be one factor considered when determining insurance pricing and eligibility, depending on the policy and underwriting.
So, the answer is not simply 25, 30, or 35.
আপনার জন্য the right age depends on your family responsibilities, income, dependents, financial goals, affordability, health and eligibility, existing protection, and the type of policy you are considering.
For one person, buying life insurance at 25 may make sense. For another, the right time may be after marriage at 30. Someone else may need to review their protection at 45 or 50.
The important thing is to avoid waiting for a “perfect” age.
🔷 Is There a Perfect Age to Buy Life Insurance?
No. There is no universal perfect age for life insurance.
Life insurance is primarily about financial protection. Your need can change as your life changes.
Think about these situations:
🔸You are financially supporting your parents.
🔸You have a spouse who depends partly on your income.
🔸You have children.
🔸You have a home or other loan.
🔸Your family depends heavily on your salary.
🔸You want to plan for children's education.
🔸You are preparing for retirement.
🔸You have long-term financial commitments.
🔸You want to review the protection you already have.
If someone depends on your income, your financial risk is not only your own.
For example, suppose a hypothetical 32-year-old earns Tk. 60,000 per month and supports a spouse, two children and an elderly parent.
If his income suddenly stops, the family may still have to pay for food, housing, education, healthcare and other expenses.
That is where life insurance can become part of a broader financial protection plan.
The question is therefore not:
“Am I old enough for life insurance?”
A better question is:
“If my income disappeared unexpectedly, who would be financially affected?”
That question can help you understand whether life insurance deserves a place in your financial plan.
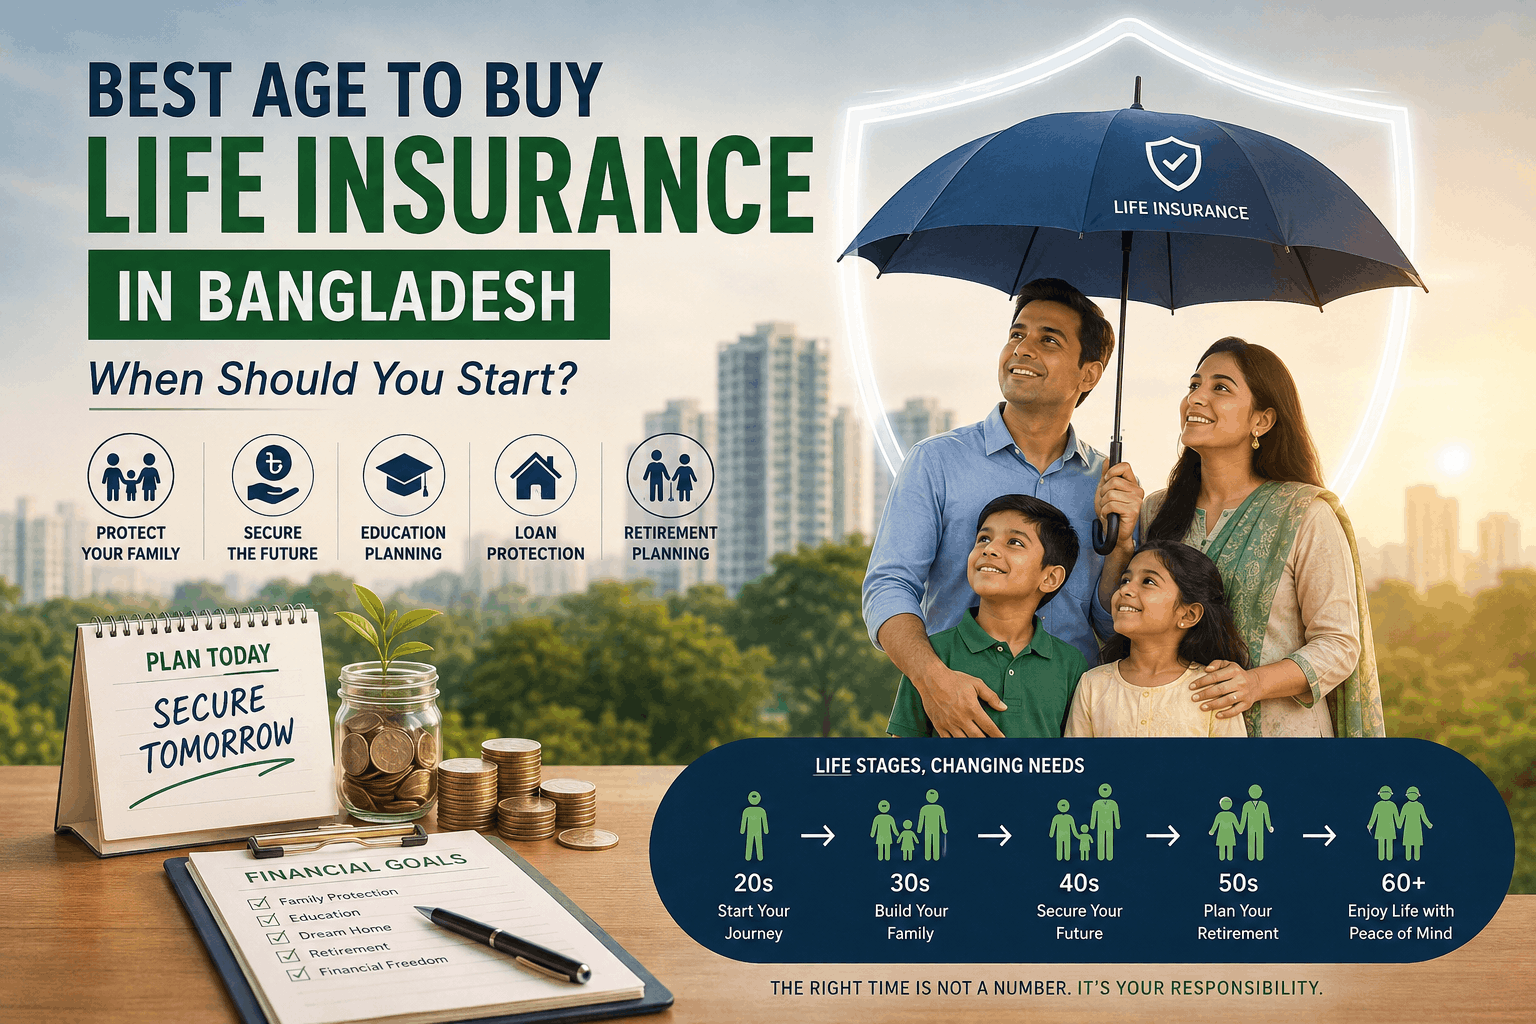
🔷 Best Age to Buy Life Insurance: 20s, 30s, 40s, 50s and Beyond
Different life stages create different financial needs.
Here is how to think about life insurance at different ages.
🔷 Life Insurance in Your 20s
Should you buy life insurance in your 20s? Potentially, yes—especially if you already have dependents, financial responsibilities, or long-term protection goals.
Being young does not automatically mean you need insurance.
A 23-year-old university graduate with no dependents, no major debt and limited income may have different priorities from a 29-year-old who supports parents and has a spouse.
However, young adults can benefit from thinking about protection early.
Why?
Because your financial responsibilities can increase quickly.
Today you may have:
🔸A salary
🔸Personal expenses
🔸Some savings
🔸Few dependents
A few years later, you may have:
🔸Marriage expenses
🔸Children
🔸Education costs
🔸Housing expenses
🔸Loans
🔸Family support responsibilities
Starting financial planning early can make it easier to build protection gradually.
Example
Suppose a hypothetical 28-year-old professional earns Tk. 50,000 per month and regularly supports his parents.
He may not have children yet, but part of his family's financial stability already depends on him.
For him, discussing life insurance may make sense even before marriage.
The key is not simply his age. It is his responsibility.
🔷 Life Insurance in Your 30s
Your 30s are often a stage when life insurance becomes especially relevant because family and financial responsibilities may increase.
For many people, this can be the decade of:
🔸Marriage
🔸Children
🔸Home purchase
🔸Education planning
🔸Increased income
🔸Family support
🔸Loans
🔸Long-term financial commitments
Suppose a hypothetical 35-year-old parent earns Tk. 80,000 a month.
His family depends on his income for everyday living. His children will need education. He may also have a housing loan.
In this situation, life insurance is not simply about “getting an insurance policy.”
It is about asking:
“How would my family manage financially if I could no longer provide my income?”
That is a much more useful way to think about life insurance.
🔷 Life Insurance in Your 40s
It is not too late to consider life insurance in your 40s.
At this stage, you may have higher income but also larger responsibilities.
Your financial priorities might include:
🔸Children's education
🔸Existing loans
🔸Family expenses
🔸Supporting parents
🔸Retirement planning
🔸Protecting accumulated financial goals
🔸Reviewing existing insurance coverage
If you already have a policy, your 40s can also be a good time to review whether your current protection still matches your responsibilities.
For example, perhaps you bought a policy at 30 when you had one child.
Now you are 42, have two children, a larger income and a home loan.
Your financial situation has changed.
Your insurance review should change with it.
🔷 Life Insurance in Your 50s
People in their 50s can still consider life insurance, but the decision should be based carefully on their needs, eligibility, affordability and available policy terms.
At this stage, retirement becomes more important.
You may be thinking about:
🔸Retirement income
🔸Outstanding loans
🔸Spouse's financial security
🔸Children's remaining education expenses
🔸Existing insurance
🔸Healthcare-related financial needs
🔸Estate or family financial planning
However, buying a new policy simply because you have reached your 50s may not always be the right decision.
First ask:
What financial problem am I trying to solve?
If your main concern is retirement, a retirement-oriented financial solution may deserve attention.
If your concern is family protection, life insurance may be relevant.
If you already have sufficient coverage, reviewing the existing policy may be more useful than automatically buying another one.
🔷 Life Insurance After 60
Life insurance after 60 may still be available in some circumstances, but eligibility, policy terms, affordability and available products can vary significantly.
At this age, the decision should be particularly careful.
Consider:
🔸Existing coverage
🔸Dependents
🔸Outstanding debts
🔸Financial assets
🔸Retirement income
🔸Policy eligibility
🔸Premium affordability
🔸Available policy term
🔸The actual purpose of buying insurance
Do not assume that everyone over 60 needs a new life insurance policy.
Instead, review the person's complete financial situation and the current policy conditions.
🔷 Does Age Affect Life Insurance Premiums?
Yes, age can be one factor considered when determining life insurance pricing, although the actual premium depends on the specific product and other factors.
In simple terms, insurance companies assess risk when determining whether and how to offer coverage.
Depending on the product, factors may include:
🔸Age
🔸Health information
🔸Coverage amount
🔸Policy term
🔸Product type
🔸Payment structure
🔸Underwriting requirements
🔸Other eligibility conditions
This is why you should not assume that a particular premium applies to everyone of the same age.
🔷 Does being younger always mean cheaper insurance?
Not necessarily in every situation.
Age can influence pricing, but it is only one consideration. Different products have different structures, and individual underwriting may also matter.
So instead of asking:
“How much will a 30-year-old pay?”
Ask:
“What is the premium for this specific product, coverage, term and applicant profile?”
That will give you a much more useful answer.
🔷 Why Do Some People Buy Life Insurance Early?
There are several practical reasons someone may consider buying life insurance earlier.
1. Financial responsibilities can grow
Your responsibilities may be relatively small at 25 and much larger at 35.
Planning before responsibilities become overwhelming can make financial management easier.
2. Age can matter in insurance pricing
Because age may be considered in underwriting and pricing, applying earlier may have advantages in some situations.
But never assume a particular saving or premium without checking the actual policy.
3. You can plan around long-term goals
Life insurance may be considered alongside goals such as:
🔸Family protection
🔸Children's education
🔸Savings
🔸Retirement planning
🔸Long-term financial security
4. Your financial plan can evolve
A policy chosen at one stage of life may not remain suitable forever.
That is why regular reviews are important.
🔷 When Should You Consider Buying Life Insurance?
A simple decision framework can help.
You may want to consider life insurance if:
Someone depends on your income
If your spouse, children, parents or another family member relies on your income, protection may become more important.
You have children
Children can create long-term financial commitments, particularly education and everyday living expenses.
You support your parents
Many Bangladeshi families provide financial support to parents. If your income is important to their financial security, this should be part of your planning.
You have significant financial obligations
Loans and other commitments do not automatically disappear if your income stops.
You have long-term financial goals
You may want to combine insurance with broader planning for family security, children's education or retirement.
Your existing coverage may no longer be enough
Major life events can change your protection needs.
Marriage, childbirth, a new loan, higher income or starting a business can all be reasons to review your plan.
🔷 How Much Life Insurance Do You Need?
There is no universal life insurance amount that is right for everyone.
The amount should reflect your family's financial needs, responsibilities, existing assets and policy objectives.
Start by asking:
🔸Who depends on my income?
🔸What are my family's monthly expenses?
🔸What debts would remain?
🔸How much would my children need for education?
🔸What financial support do my parents need?
🔸What existing savings or investments are available?
🔸How much insurance can I comfortably afford?
🔸How long would my family need financial support?
A simple hypothetical example
Suppose Rahim earns Tk. 70,000 per month.
His family depends on his income. He has two children and an outstanding home loan.
Instead of choosing a policy simply because someone says, “Take Tk. 1 crore,” he should first calculate his actual responsibilities and compare them with his existing assets and protection.
The objective is not to buy the biggest policy.
It is to find appropriate protection that fits his financial situation and remains affordable.
🔷 How to Choose the Right Life Insurance Policy in Bangladesh
Choosing a policy is more important than simply choosing an age.
Before buying, compare:
🔸 Coverage
Understand what financial protection the policy provides.
🔸Policy term
Check how long the policy remains in force and what happens at the end of the term.
🔸Premium or contribution
Make sure the payment fits comfortably within your regular budget.
A policy that becomes difficult to maintain can create financial stress.
🔸 Benefits
Read exactly what benefits are provided and under what conditions.
🔸Exclusions
Understand what the policy does not cover.
🔸Eligibility
Check age limits, health requirements and other applicable conditions.
🔸Payment frequency
Understand whether payments are monthly, quarterly, half-yearly, yearly or structured differently.
🔸Maturity and death benefits
Where applicable, understand how these benefits work and when they become payable.
🔸Nominee provisions
Make sure you understand how nominee information is recorded and maintained.
🔸Claim process
Understand what documents and procedures may be required if a claim occurs.
🔸Surrender or loan facilities
If the policy provides such facilities, understand the conditions before assuming they are immediately available.
🔸Affordability
Do not buy a policy simply because an agent or advertisement recommends it.
Your policy should fit your budget and financial objectives.
Cheaper does not automatically mean better.
🔷Why Consider National Life Insurance PLC?
National Life Insurance PLC can be one provider for Bangladeshi consumers to explore when researching life insurance and related financial protection solutions.
Its current official product section lists categories including Child Insurance, Pension Policy, Savings Policy, DPS, Whole Life, Survival Benefit (SB), Islami Takaful, FDR and Group Insurance.
Its 2024 Annual Report also describes a broader portfolio including endowment insurance, anticipated endowment products, child protection, pension insurance, whole life, monthly savings insurance, children education security, family savings and income insurance, Takaful products and group insurance.
That variety matters because different families have different goals.
Someone in their 20s may be thinking mainly about building financial discipline and protection.
A parent in their 30s may be more concerned about children's future.
Someone in their 40s may be reviewing family protection and retirement preparation.
A person approaching retirement may have completely different priorities.
The right product should therefore come after identifying the financial goal, not before.
🔷 National Life Insurance PLC Products for Different Financial Needs
National Life Insurance PLC currently presents several product categories that may be relevant to different financial goals. Exact benefits, eligibility, premiums, terms and conditions should always be checked against the current official product documents.
🔸Child Insurance
Parents may explore child-focused insurance options when planning for children's future financial needs.
The company's published portfolio includes child protection and children education-related products.
🔸Pension Policy
People thinking about retirement may explore pension-oriented insurance.
National Life Insurance PLC's published product portfolio includes Pension Insurance and Assurance Cum Pension Policy.
🔸Savings Policy
Savings-oriented insurance may be relevant for people who want structured long-term saving alongside applicable insurance features.
The exact structure and benefits depend on the specific product.
🔸DPS
DPS is listed among National Life Insurance PLC's current product categories.
However, remember that a savings product and life insurance do not necessarily serve exactly the same purpose.
🔸Whole Life
Whole Life is another category listed by National Life Insurance PLC.
It should not automatically be treated as identical to a temporary protection product or a savings product. Review its specific coverage, premium structure and conditions before deciding.
🔸Survival Benefit
Survival Benefit products may be relevant to people looking for a particular combination of insurance protection and benefits during the policy period, depending on the product structure.
Always check the actual benefit schedule and conditions.
🔸Islami Takaful
For customers looking for Shariah-oriented insurance arrangements, National Life Insurance PLC offers an Islami Takaful category. Its 2024 Annual Report lists several Takaful products, including three-payment, four-payment, one-payment endowment and monthly savings products.
🔸FDR
FDR is also listed on the company's current product page.
But FDR should not be confused with life insurance. The purpose, protection, access, return structure and conditions can be different.
🔸Group Insurance
Employers and organizations may also explore group insurance options. National Life Insurance PLC's current group-insurance section lists Group Term Insurance, Group Endowment Insurance, Group Economy Insurance, Group Anticipated Insurance and other group-related products.
The best choice depends on the actual financial objective.
🔷 Common Life Insurance Mistakes to Avoid
🔸 Waiting for the “perfect age”
There may never be a perfect moment.
Review your situation when major financial responsibilities appear.
🔸 Buying more than you can afford
A large policy is not useful if the payment becomes difficult to maintain.
🔸Choosing only by price
The cheapest premium may not provide the protection or benefits you actually need.
🔸Not reading exclusions
Always understand what is and is not covered.
🔸Not understanding policy terms
Never sign a policy document simply because someone explains it verbally.
🔸Read the official terms.
Providing inaccurate information
Give accurate information during the application process.
🔸Ignoring nominee information
Review nominee details carefully and update them when appropriate.
🔸Never reviewing your policy
Marriage, children, loans, higher income and changing family responsibilities can change your needs.
🔸Buying because of advertising alone
An advertisement can introduce a product.
It should not replace your own evaluation.
🔸Assuming all insurance products are the same
Term protection, whole life, endowment, savings-oriented insurance, pension-related products and Takaful can have very different structures.
Understand the purpose before choosing.
🔷 Age or Life Stage: Which Matters More When Buying Life Insurance?
Your life stage can matter more than your exact age when deciding whether you need life insurance.
Two people can both be 30 years old but have completely different insurance needs.
One may be single, have no dependents and have substantial savings.
Another may have a spouse, two children, elderly parents to support and a home loan.
Same age. Very different financial responsibilities.
That is why searching for the best age to buy life insurance should only be the starting point.
Ask yourself:
🔸Does anyone depend on my income?
🔸Do I have debts or long-term financial commitments?
🔸Would my family struggle if my income stopped?
🔸Do I have children or parents who depend on me?
🔸Do I already have enough financial protection?
🔸What future goals am I trying to protect?
Key takeaway: Age can affect insurance eligibility and pricing, but your responsibilities help determine whether you actually need coverage.
🔷 Do I Need Life Insurance If I Am Single?
Being single does not automatically mean you do not need life insurance.
The better question is whether anyone would face a financial problem if you were no longer able to provide your income.
For example, a single professional in Bangladesh may regularly support his or her parents.
আরেকজন হয়তো ছোট ভাই-বোনের পড়াশোনার খরচ দেন।
Someone else may have a loan or another financial obligation.
In these cases, being unmarried does not mean having no financial responsibilities.
On the other hand, if you are single, have no dependents, have no significant obligations and already have sufficient financial resources for your needs, life insurance may not be your most urgent financial priority.
Review your actual situation rather than buying a policy simply because you have reached a particular age.
A simple question to ask
“Would anyone be financially affected if my income disappeared?”
If the answer is yes, it may be worth exploring life insurance.
🔷 When Might Life Insurance Not Be an Immediate Priority?
Life insurance is useful for many people, but not everyone needs to buy a policy immediately.
This is an important point because a trustworthy financial decision should consider both reasons to buy and reasons to wait or explore other priorities.
Life insurance may be less urgent if:
🔸Nobody depends financially on you
🔸You have no significant financial obligations
🔸Your current budget cannot 🔸comfortably support the premium
🔸You already have adequate financial protection
🔸Another financial need requires more immediate attention
🔸The policy being offered does not match your actual goal
For example, suppose a hypothetical 24-year-old has just started working and has no dependents or debts.
If most of that person's income is needed for essential living expenses, emergency savings and basic financial stability, buying a large insurance policy may not be the first priority.
That does not mean life insurance will never become relevant.
It means financial decisions should match current needs and affordability.
As responsibilities change, review the situation again.
🔷 Should You Buy Life Insurance Now or Wait?
Consider buying life insurance now if you already have financial responsibilities that need protection. Waiting may make more sense if you do not currently need the protection or cannot comfortably maintain the policy.
A simple five-question test can help.
Ask yourself:
🔸Does anyone rely on my income?
🔸Would my family struggle with debts or expenses without me?
🔸Do I have long-term responsibilities such as children's education or parental support?
🔸Can I comfortably afford the premium for the required period?
🔸Does the policy actually solve the financial problem I am concerned about?
If you answer yes to several of these questions, it may be a good time to explore suitable life insurance options.
If most answers are no, you may need further financial planning before deciding.
Do not buy simply because someone tells you:
“এখন না করলে পরে অনেক দেরি হয়ে যাবে।”
Instead, understand your need, compare suitable products and read the policy terms.
🔷 Which Life Events Should Trigger a Life Insurance Review?
You should review your life insurance whenever a major life event significantly changes your income, dependents, debts or financial responsibilities.
Buying a policy should not be a “set it and forget it” decision.
Your life at 28 may look very different from your life at 38.
Consider reviewing your protection after:
🔸 Getting married
Marriage may create shared expenses, financial goals and income dependency.
🔸Having a child
A child can add years of living, healthcare and education-related financial responsibilities.
🔸Starting to support parents
If your parents begin depending more heavily on your income, your protection needs may change.
🔸Buying a home or taking a major loan
Large financial obligations can increase the amount of money your family may need if your income stops.
🔸Receiving a major income increase
A higher income can mean a higher standard of living and greater family dependency on that income.
🔸Starting a business
Business owners may have additional responsibilities involving loans, employees, partners or family income.
🔸Approaching retirement
Your focus may gradually shift from income replacement toward retirement planning, existing liabilities and family financial security.
🔸A major change in your family
Marriage, childbirth, divorce, the death of a dependent or children becoming financially independent can all change how much protection you need.
Practical rule: Review your financial protection after a major life change and periodically even when nothing dramatic has happened.
🔷 Do Self-Employed People Need Life Insurance?
Self-employed people may need life insurance if their family depends on their income or if they have business-related financial responsibilities.
This can be particularly relevant in Bangladesh, where many people earn through:
🔸Small businesses
🔸Freelancing
🔸E-commerce
🔸Professional services
🔸Family businesses
🔸Contract work
🔸Agriculture or trading
🔸Independent consultancy
Unlike some salaried employees, a self-employed person may not have employer-provided insurance or other workplace benefits.
Suppose a hypothetical online business owner earns Tk. 90,000 in an average month and supports a spouse, children and parents.
The question is not whether that person receives a formal salary.
The question is whether the household depends on that income.
Self-employed people should consider:
🔸Family living expenses
🔸Business debts
🔸Personal loans
🔸Emergency savings
🔸Existing insurance
🔸Income stability
🔸Children's future expenses
🔸How long dependents may need financial support
The appropriate policy should still depend on affordability, eligibility and actual financial needs.
🔷 Does a Stay-at-Home Parent Need Life Insurance?
A stay-at-home parent may also have an economic value to the family even without earning a formal salary.
Think about the work a parent may perform every day:
🔸Childcare
🔸School support
🔸Household management
🔸Cooking
🔸Transportation
🔸Caring for family members
If that work suddenly had to be replaced with paid services, the household could face additional costs.
So life insurance planning should not always focus only on the person with the largest salary.
A family should consider the financial impact of losing each person's contribution, whether that contribution comes through income or unpaid household responsibilities.
🔷 What Happens If You Wait to Buy Life Insurance?
Waiting does not automatically mean you are making a mistake, but your available options may change over time.
Age is one factor insurers may consider when assessing pricing and eligibility. Health, product type, coverage, policy term and underwriting requirements may also matter.
That means a policy available to you today may not necessarily have the same pricing, conditions or eligibility requirements several years later.
However, this does not mean you should rush into buying an unsuitable policy.
A better approach is:
🔸Decide whether you currently need protection.
🔸Estimate the financial responsibility you want to protect.
🔸Check what you can comfortably afford.
🔸Compare relevant insurance options.
🔸Review eligibility and underwriting requirements.
🔸Read exclusions and official policy conditions.
🔸Make a decision based on your situation—not fear.
Key takeaway: Do not delay an important financial decision indefinitely, but do not rush into the wrong policy either.
🔷 First Salary, Marriage or First Child: When Is the Right Time?
There is no rule that says life insurance must begin with your first salary, marriage or first child. The right trigger is usually the point when meaningful financial dependency or long-term responsibility begins.
Here is a simple way to think about it.
🔸First salary
Consider insurance if your income already supports parents or other dependents.
🔸Marriage
Review your needs if you and your spouse begin depending financially on each other.
🔸First child
Protection can become more important because your family now has a longer period of financial responsibility ahead.
🔸Home loan
Consider how the outstanding liability would affect your family if your income disappeared.
🔸Starting a business
Review both personal and business-related financial obligations.
🔸Approaching retirement
Reassess whether your existing protection still matches your needs and whether retirement-oriented planning deserves greater attention.
Instead of choosing life insurance because you reached a certain birthday, connect the decision to real financial responsibilities.
🔷 7 Signs It May Be Time to Review Life Insurance
It may be time to review your life insurance if:
🔸Someone now depends on your income.
🔸You recently got married.
🔸You had a child.
🔸You started financially supporting your parents.
🔸You took a major loan.
🔸Your income or household expenses changed significantly.
🔸Your existing policy no longer reflects your current responsibilities.
A policy that was suitable five or ten years ago may not necessarily match your financial life today.
Review first. Then decide whether you need more coverage, different protection or no change at all.
🔷 Life Insurance Readiness Check: Are You Ready to Buy?
Before exploring a policy from National Life Insurance PLC or another insurer, answer these questions:
Financial need:
Who am I trying to protect?
Income dependency:
Who currently relies on my earnings?
Financial impact:
What expenses would continue if my income stopped?
Existing protection:
What savings, insurance or other resources already exist?
Goal:
Am I primarily looking for family protection, savings, children's planning, retirement planning or another objective?
Affordability:
Can I maintain the required payments without putting pressure on essential household expenses?
Policy understanding:
Do I understand the benefits, exclusions, policy term, premium requirements and claim conditions?
If you cannot answer these questions yet, gather more information before choosing a product.
If you can answer them clearly, comparing suitable options becomes much easier.
For readers considering National Life Insurance PLC, the next step can be to explore the company's currently available products according to the financial goal you identified, then verify the exact eligibility, premium, benefits, exclusions and other terms from the official product documents before applying.
🔷 Final Thoughts: When Should You Start?
The best age to buy life insurance is not necessarily a particular birthday.
For many people, the right time becomes clearer when financial responsibility begins.
Maybe you get married.
Maybe your first child is born.
Maybe your parents begin depending more heavily on you.
Maybe you take a large loan.
Maybe you start thinking seriously about retirement.
These moments can change the answer.
If you are young and have few responsibilities, you can still learn about life insurance and understand your options.
If you already have dependents, it may be worth reviewing your protection sooner rather than later.
And if you are in your 40s or 50s, do not assume you are “too late.” Instead, examine your current financial position, existing coverage, goals, affordability and available policy options.
The most useful question is not:
“What is the perfect age to buy life insurance?”
It is:
“What financial responsibilities do I have today, and how would my family manage if my income were suddenly unavailable?”
That question can lead to a much better financial decision.
If you are considering life insurance in Bangladesh, explore the available options from National Life Insurance PLC, compare products according to your financial goals, and read the current official policy documents carefully before making a commitment.
← Back to Insights
NLI Archive / 2026
Trending Analysis
Best Age to Buy Life Insurance in Bangladesh: When Should You Start?
N
NLI Editorial
© National Life Insurance Co. Ltd.
Share:
FB
LN